 Gilberto de la Fuente
Two households choose separately. One cleaner pays the combined tax.
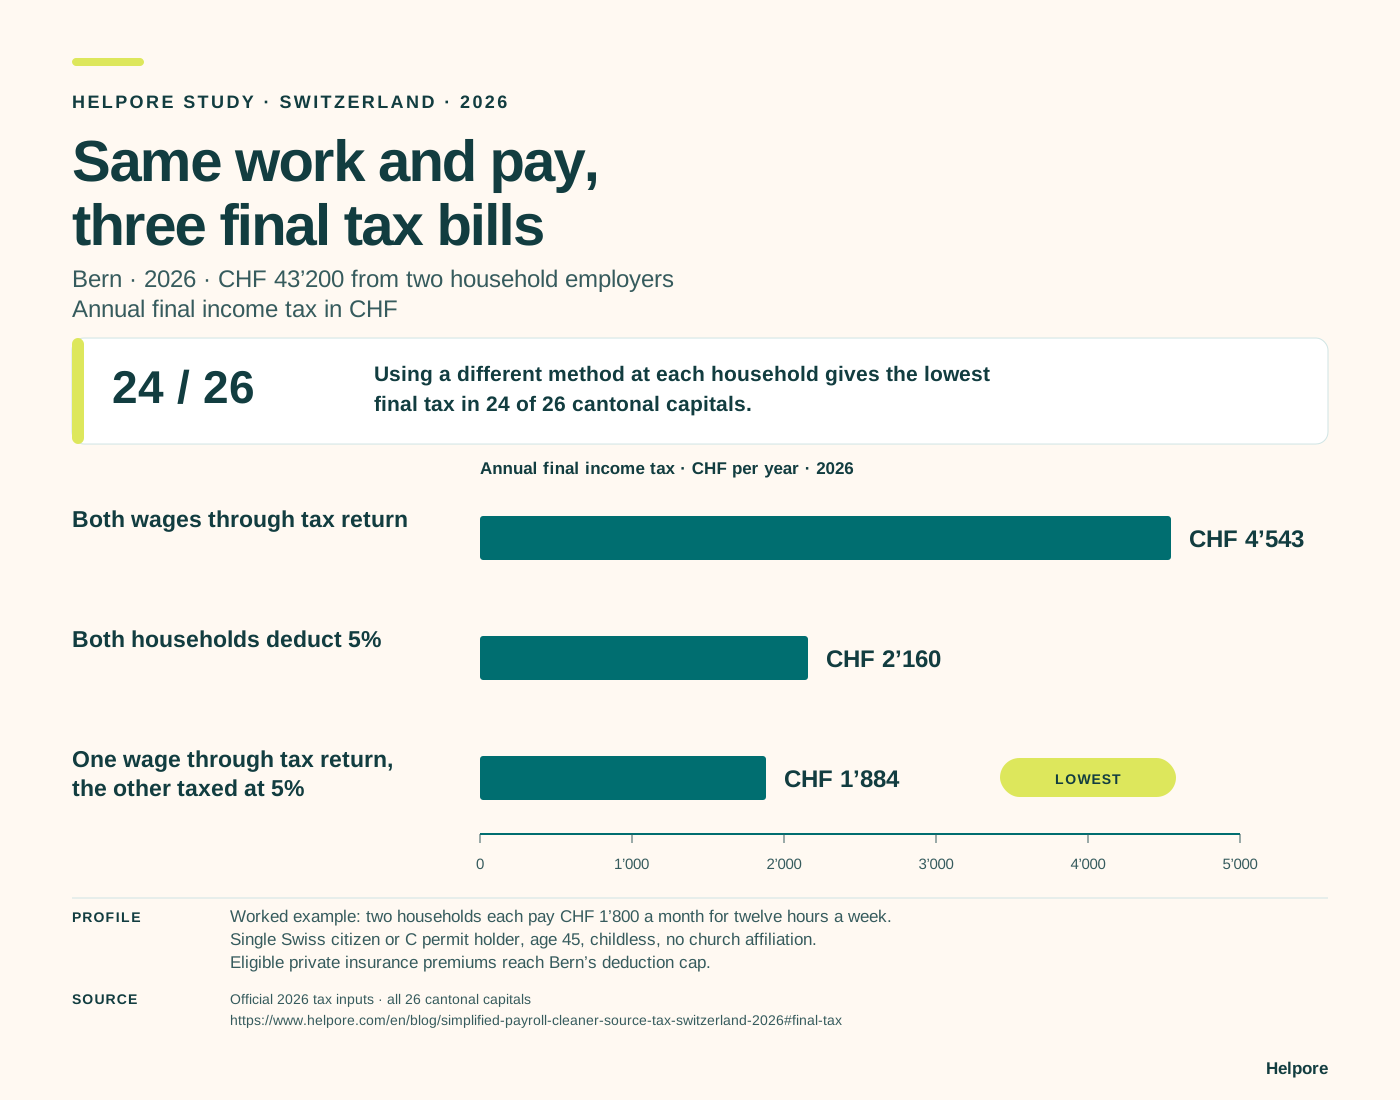
In Bern, final income tax is CHF 4’543 when both wages are taxed through the annual tax return, CHF 2’160 when both households deduct 5%, and CHF 1’884 when one wage goes through the tax return and the other is taxed at 5%. The person, work, hours and pay do not change.
The total with one method at each household is different because only one wage is added to the cleaner’s taxable income and tax rate. The other wage has already received its final 5% tax through the household that paid it.
Repeating the same calculation in every cantonal capital, using a different method at each household gives the lowest final tax in 24 of 26. Geneva and Zug are the exceptions, where taxing both wages through the annual return gives the lowest total.
Same work and pay, three final tax bills
Bern · 2026Bern · 2026 · CHF 43’200 from two household employers. Annual final income tax in CHF.
Using a different method at each household gives the lowest final tax in 24 of 26 cantonal capitals.
Worked example: two households each pay CHF 1’800 a month for twelve hours a week. The cleaner is a single Swiss citizen or C permit holder, age 45, childless, with no church affiliation and eligible private insurance premiums at Bern’s deduction cap.
Download this comparison as SVGDownload this comparison as PNGYou may reproduce this Helpore chart in editorial coverage with credit to Helpore. Keep the source, year, model and units visible.
| City | Both wages through tax return | One wage through tax return, the other taxed at 5% | Both households deduct 5% | Lowest result |
|---|---|---|---|---|
| Zurich | CHF 2’437 | CHF 1’493 | CHF 2’160 | Different method at each household |
| Bern | CHF 4’543 | CHF 1’884 | CHF 2’160 | Different method at each household |
| Zug | CHF 833 | CHF 1’080 | CHF 2’160 | Both through tax return |
The table repeats the same worked example in each cantonal capital.
All 26 cantonal capitals for the same cleaner and pay
| Capital | Both wages through tax return | One wage through tax return, the other taxed at 5% | Both households deduct 5% |
|---|---|---|---|
| Aarau (AG) | CHF 2’683 | CHF 1’159Lowest tested | CHF 2’160 |
| Appenzell (AI) | CHF 2’607 | CHF 1’566Lowest tested | CHF 2’160 |
| Herisau (AR) | CHF 3’803 | CHF 1’869Lowest tested | CHF 2’160 |
| Bern (BE) | CHF 4’543 | CHF 1’884Lowest tested | CHF 2’160 |
| Liestal (BL) | CHF 3’339 | CHF 1’315Lowest tested | CHF 2’160 |
| Basel (BS) | CHF 3’106 | CHF 1’080Lowest tested | CHF 2’160 |
| Fribourg (FR) | CHF 3’858 | CHF 1’527Lowest tested | CHF 2’160 |
| Genève (GE) | CHF 546Lowest tested | CHF 1’080 | CHF 2’160 |
| Glarus (GL) | CHF 3’077 | CHF 1’515Lowest tested | CHF 2’160 |
| Chur (GR) | CHF 2’070 | CHF 1’080Lowest tested | CHF 2’160 |
| Delémont (JU) | CHF 3’471 | CHF 1’555Lowest tested | CHF 2’160 |
| Luzern (LU) | CHF 2’482 | CHF 1’080Lowest tested | CHF 2’160 |
| Neuchâtel (NE) | CHF 4’609 | CHF 1’476Lowest tested | CHF 2’160 |
| Stans (NW) | CHF 2’689 | CHF 1’270Lowest tested | CHF 2’160 |
| Sarnen (OW) | CHF 3’378 | CHF 1’541Lowest tested | CHF 2’160 |
| St. Gallen (SG) | CHF 3’413 | CHF 1’459Lowest tested | CHF 2’160 |
| Schaffhausen (SH) | CHF 2’610 | CHF 1’354Lowest tested | CHF 2’160 |
| Solothurn (SO) | CHF 3’692 | CHF 1’394Lowest tested | CHF 2’160 |
| Schwyz (SZ) | CHF 1’541 | CHF 1’083Lowest tested | CHF 2’160 |
| Frauenfeld (TG) | CHF 3’111 | CHF 1’306Lowest tested | CHF 2’160 |
| Bellinzona (TI) | CHF 1’889 | CHF 1’080Lowest tested | CHF 2’160 |
| Altdorf UR (UR) | CHF 3’081 | CHF 1’291Lowest tested | CHF 2’160 |
| Lausanne (VD) | CHF 3’214 | CHF 1’080Lowest tested | CHF 2’160 |
| Sion (VS) | CHF 2’849 | CHF 1’090Lowest tested | CHF 2’160 |
| Zug (ZG) | CHF 833Lowest tested | CHF 1’080 | CHF 2’160 |
| Zürich (ZH) | CHF 2’437 | CHF 1’493Lowest tested | CHF 2’160 |
Personal details and full calculation method
The model compares the same gross work and hours. Each of two genuine household employers pays CHF 21’600 for 12 hours a week. The worker is a Swiss citizen or C permit holder, single, age 45, childless and living alone, with no church affiliation, wealth, other income, pillar 3a contribution, voluntary occupational pension contribution or rent deduction. Ordinary payroll includes the modelled employee social deductions and nonoccupational accident premium. Simplified wages stay outside ordinary taxable income and its rate calculation, with the final 5% tax added separately. Personal deductions apply once. Where a cantonal rule does not specify the part time calculation, the model uses ordinary weekly hours divided by 40. The lowest arrangement did not change across the three tested work expense protocols or either payroll rounding method.
The 24 of 26 finding assumes eligible private insurance premiums reach each local deduction cap. In a Geneva check with CHF 4’560 of eligible premiums, final income tax with both ordinary payroll is CHF 2’766 while the mixed result stays CHF 1’080, so mixed is lower.
Across CHF 21’600, CHF 43’200 and CHF 54’000 and two to five equal employers, the lowest tested arrangement changes with pay, employer count and capital. The CHF 54’000 two employer case is excluded from the comparable model without compulsory occupational pension cover.
Official ESTV tax calculator · Zurich source tax and ordinary assessment guidance · Zug tax law
The comparison above is about annual final income tax for a Swiss citizen or C permit holder. The next section asks a separate question for a B permit holder: how much tax each household deducts from pay during the year.
For a B permit holder, the difference appears during the year
This analysis compares source tax deductions, not the final tax model above. Two independent households each pay the same single, childless B permit holder CHF 1’800 a month for twelve hours a week throughout 2026.
When both jobs use ordinary payroll, each household uses the worker’s combined employment to set the source tax rate on the wage it pays. When Household A uses the simplified procedure, that job is taxed separately at 5% and no longer raises the rate applied by Household B. Household B changes nothing about its own job, but its annual deduction falls.
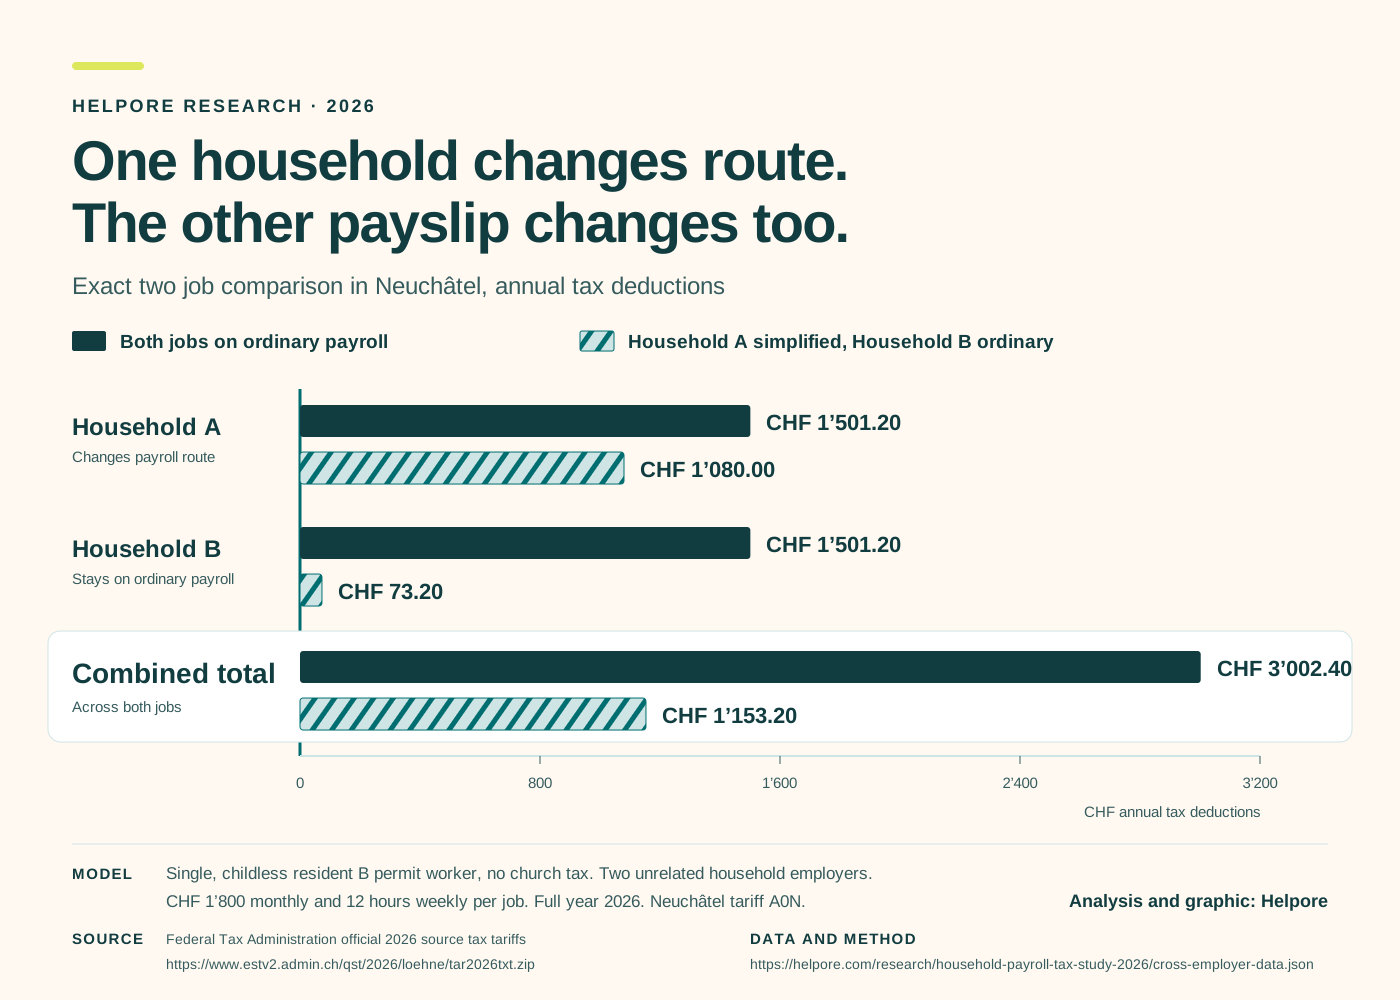
In the Neuchâtel example, total annual tax deducted across both jobs falls from CHF 3’002.40 to CHF 1’153.20. Household B alone deducts CHF 1’428 less. These figures measure deductions from wages during the year.
One household changes route. The other payslip changes too.
Neuchâtel · 2026Annual tax deducted. Pay stays CHF 1’800 a month per job, for twelve hours a week each.
| Household | Both ordinary | A simplified, B ordinary |
|---|---|---|
| Household AProcedure changes | CHF 1’501.20Ordinary payroll | CHF 1’080.00Simplified payroll |
| Household BProcedure stays the same | CHF 1’501.20Ordinary payroll | CHF 73.20Still ordinary payroll |
| Both jobsTotal tax deducted | CHF 3’002.40 | CHF 1’153.20 |
Household B deducts CHF 1’428 less in tax. Across both jobs, annual deductions fall by CHF 1’849. These are tax deductions, not wages or net pay.
Read the two job results for all 26 cantons
Download the two job chart (SVG)Download the two job chart (PNG)You may reproduce this Helpore chart in editorial coverage with credit to Helpore. Keep the source, year, model and units visible.
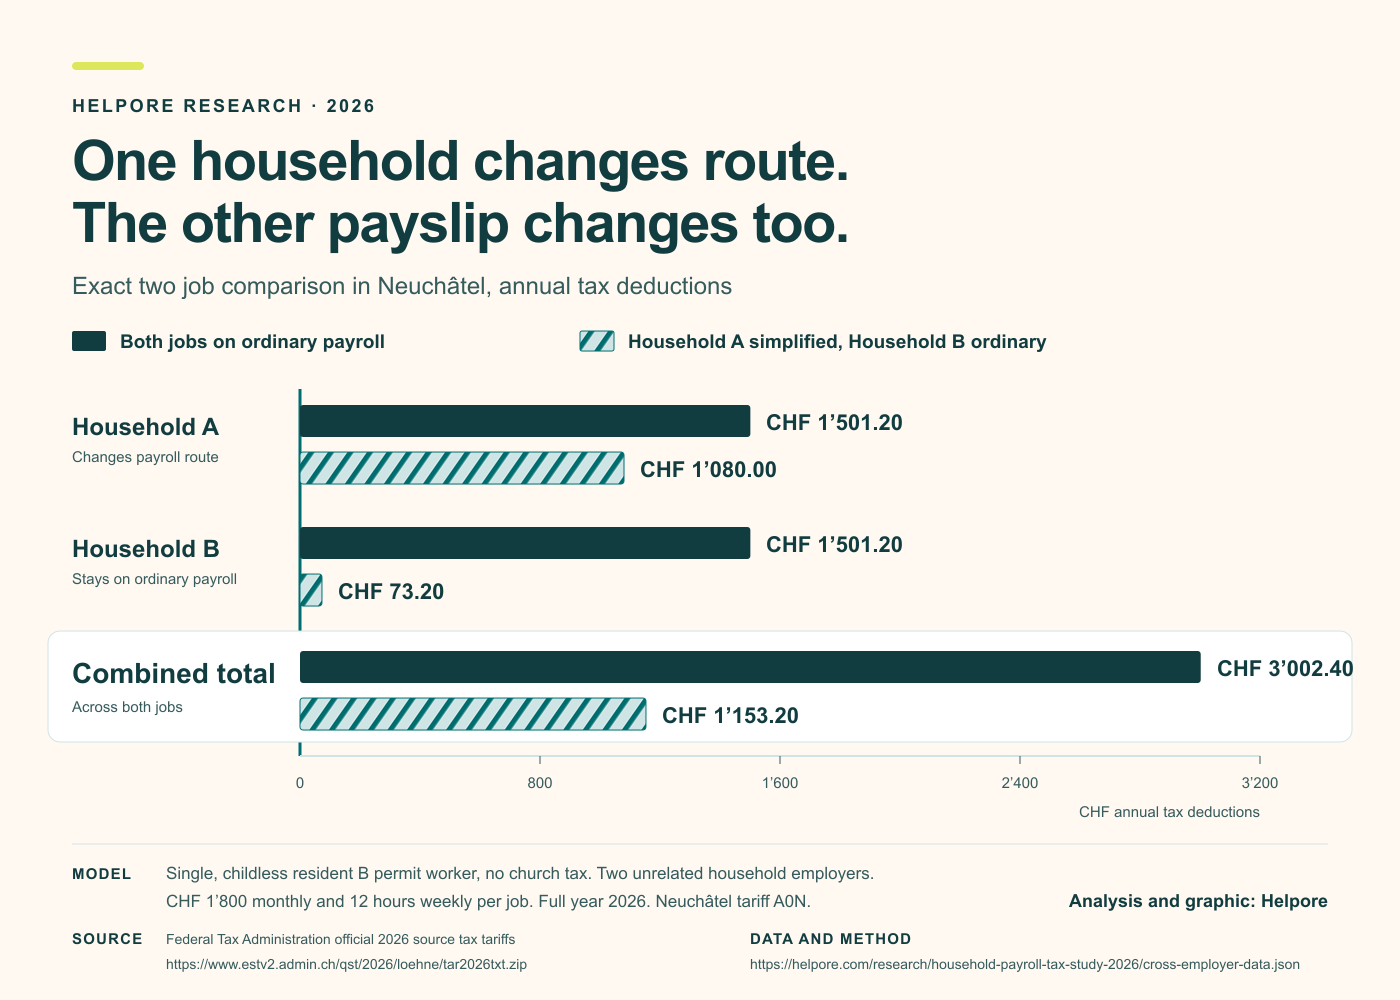
With two ordinary jobs, each household uses the worker's combined workload to set its tax rate. When the only other job uses the simplified procedure, that job no longer raises the ordinary job's rate basis. The rule is in Circular 45, section 6.4.
Each household chooses its own lawful procedure. A worker can ask or negotiate, but cannot make that choice for an employer. An existing employer moving from ordinary to simplified payroll must notify its compensation office before year end. The change starts with the new calendar year and is not retrospective.
What changes when the same income is divided among three households
The following comparison returns to source tax deductions for the defined B permit model. It does not extend the final tax finding above.
Three households each pay CHF 1’500 a month for ten hours a week. Together, the jobs provide CHF 4’500 in gross monthly pay.
Across the 26 canton models, all ordinary payroll deducts an average CHF 1’899 more a year than one ordinary and two simplified payrolls, counting each canton once and including the negative results in Schwyz and Zug.
Same work and pay,
three payroll outcomes
Neuchâtel · 2026Insurance premiums and service fees are not included.
The result changes with pay and employer count
At total monthly pay of CHF 2’700, CHF 3’600, CHF 4’500 and CHF 5’400 across three equal jobs, a mixed route deducts less than all ordinary payroll in 6, 22, 24 and 25 canton models respectively.
The all simplified comparison is different. It deducts less than all ordinary payroll in 1, 14, 23 and 24 canton models at those four pay levels.
The CHF 1’899 result is the signed mean of 26 canton results, including the negative results in Schwyz and Zug. It gives each canton equal weight and is not population weighted.